Chart of accounts for rental property (with a free template)
By Anthony Basile -
A chart of accounts is the list of categories your bookkeeping sorts every dollar into: the bank accounts you hold, what you owe, the income you earn and each kind of expense. For a rental property, a good one does two jobs at once. It tells you how each property is performing during the year, and at tax time it hands your preparer totals that already line up with Schedule E, the IRS form where rental income and expenses are reported.
This guide explains what goes into a chart of accounts, gives you a numbering system built for rental property, walks through a year of numbers for an invented duplex and links a free chart of accounts template (CSV) that opens in Excel, Google Sheets or Numbers.
What is a chart of accounts?
Every bookkeeping system, from a spreadsheet to accounting software, starts with a chart of accounts. Each account has a number and a name, and each one belongs to one of five types:
- Assets: what the business owns, such as bank accounts, rent receivable and the building itself.
- Liabilities: what it owes, such as the mortgage and the security deposits you hold for tenants.
- Equity: the owner's stake, including money you put in and money you take out.
- Income: rent, late fees and other money the property earns.
- Expenses: the costs of running the property, from insurance to repairs.
Income and expenses produce your profit and loss statement. Assets, liabilities and equity produce your balance sheet. When every transaction lands in one account, both reports come straight from the books.
How to number the accounts
Most charts of accounts group the types by number range, so the account number alone tells you where it belongs. Leave gaps between numbers so you can add accounts later without renumbering.
| Range | Type | Examples |
|---|---|---|
| 1000-1999 | Assets | Operating bank account, security deposit account, rent receivable, buildings, land |
| 2000-2999 | Liabilities | Mortgage payable, security deposits held, prepaid rent |
| 3000-3999 | Equity | Owner contributions, owner draws, retained earnings |
| 4000-4999 | Income | Rent, late fees, other income |
| 5000-5999 | Expenses | Insurance, repairs, property taxes, mortgage interest, depreciation |
Income and expense accounts that follow Schedule E
The most useful choice you can make is to name your income and expense accounts after the lines on Schedule E. Then the year-end totals copy straight across, and nobody has to re-sort a year of transactions in March. These are the lines on recent versions of the form; check the current year's form with your tax professional before you file.
| Account | Name | Schedule E line |
|---|---|---|
| 4000 | Rent income | 3 |
| 4100 | Late fees | 3 |
| 4200 | Other income | 3 |
| 5000 | Advertising | 5 |
| 5010 | Auto and travel | 6 |
| 5020 | Cleaning and maintenance | 7 |
| 5030 | Commissions | 8 |
| 5040 | Insurance | 9 |
| 5050 | Legal and other professional fees | 10 |
| 5060 | Management fees | 11 |
| 5070 | Mortgage interest | 12 |
| 5080 | Other interest | 13 |
| 5090 | Repairs | 14 |
| 5100 | Supplies | 15 |
| 5110 | Property taxes | 16 |
| 5120 | Utilities | 17 |
| 5130 | Depreciation | 18 |
| 5140 | Other expenses | 19 |
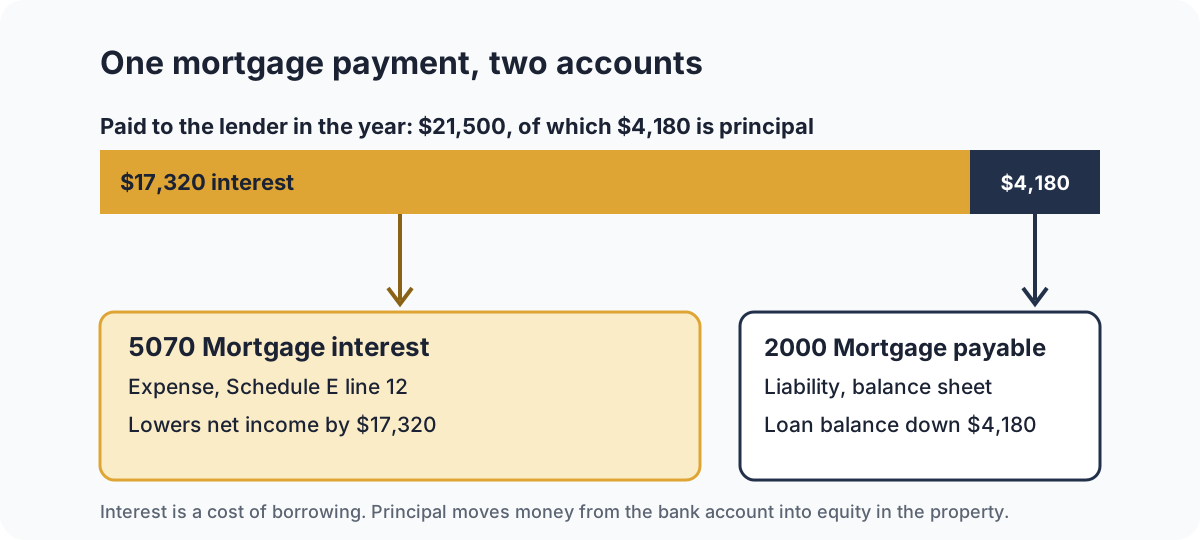
Two accounts trip people up. The mortgage payment splits in two: the interest goes to 5070, and the principal reduces 2000 Mortgage payable, because paying down a loan builds your equity in the property. And security deposits go to 2100 Security deposits held, a liability, because you hold that money for the tenant until they move out.
A worked example: the Birch Lane duplex
Here is one year of books for an invented duplex. Each side rents for $1,700 a month, the owner manages it themselves, and coin laundry in the basement brings in a little extra.
| Account | Amount |
|---|---|
| 4000 Rent income (2 units x $1,700 x 12) | $40,800 |
| 4100 Late fees | $75 |
| 4200 Other income (laundry) | $480 |
| Total income | $41,355 |
| 5000 Advertising | $120 |
| 5020 Cleaning and maintenance | $1,350 |
| 5040 Insurance | $1,740 |
| 5050 Legal and other professional fees | $650 |
| 5070 Mortgage interest | $17,320 |
| 5090 Repairs | $2,860 |
| 5100 Supplies | $310 |
| 5110 Property taxes | $4,920 |
| 5120 Utilities | $1,080 |
| 5130 Depreciation | $9,091 |
| Total expenses | $39,441 |
| Net income | $1,914 |
The same books answer three different questions:
- Taxable rental income starts from the net income line: $41,355 - $39,441 = $1,914. Depreciation of $9,091 is a large part of the expenses, and it costs no cash this year.
- Net operating income leaves out mortgage interest and depreciation: $41,355 - $13,030 of operating expenses = $28,325. That is the number the NOI calculator works out, and the one buyers use for a cap rate.
- Cash flow subtracts the whole mortgage payment from NOI. The owner paid $17,320 of interest and $4,180 of principal, $21,500 in all, so cash flow was $28,325 - $21,500 = $6,825 for the year. A lender would see a debt service coverage ratio of $28,325 / $21,500 = 1.32, which you can check with the DSCR calculator.
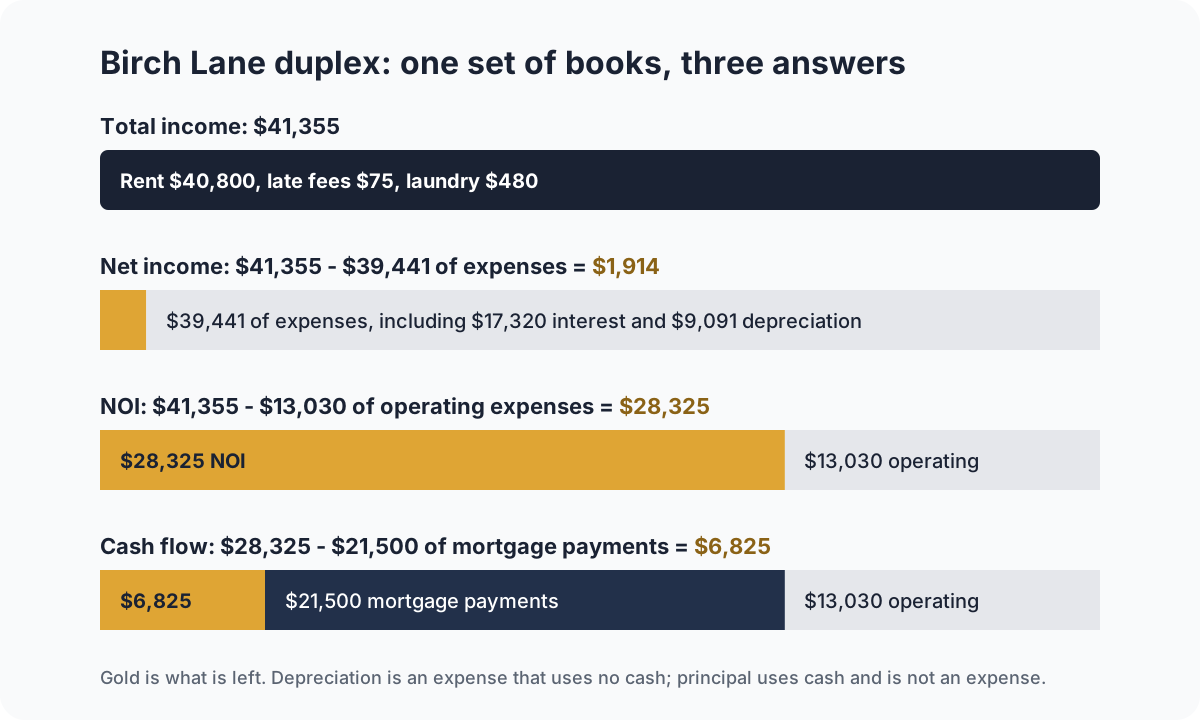
Without separate accounts for interest, principal and depreciation, those three numbers blur together, and a profitable year can look like a loss or the other way around.
How to set up your chart of accounts
- Download the template. The chart of accounts template (CSV) has every account above, its type, its Schedule E line and the Birch Lane amounts, with blank rows for your own additions.
- Use one chart for every property. Keep the account list the same everywhere and tag each transaction with its property. Your reports can then show one property or all of them, and the totals always compare like with like.
- Open separate bank accounts. Keep rental money apart from personal money, and keep security deposits in their own account if you can. Each bank account gets its own asset account.
- Add accounts sparingly. A short list you use consistently beats a long one where similar costs land in different places. If an expense does not fit, use 5140 Other expenses and write a note.
- Split every mortgage payment. Record the interest in 5070 and the principal against 2000 Mortgage payable. Your lender's annual statement shows the interest total to check against.
- Reconcile monthly. Match each bank account in your books to the bank statement, and categorize anything left over while you still remember what it was.
- Hand it to your tax professional. Ask them to confirm the accounts before the first year closes, especially how to split repairs from improvements, since that choice changes what goes on line 14 and what gets depreciated.
Frequently asked questions
What is a chart of accounts in simple terms?
It is the list of buckets your bookkeeping sorts money into, each with a number and a name. Rent goes in one bucket, insurance in another, the mortgage balance in a third. The totals in those buckets become your profit and loss statement and your balance sheet.
How many accounts does a rental property need?
Most small portfolios run well on 25 to 35 accounts, about what the template holds. Start with the Schedule E expense lines, your bank accounts, the mortgage and security deposits, then add an account only when you keep wanting a number the list does not give you.
Should each property have its own chart of accounts?
Use one chart for all of them and tag each transaction with its property. Separate charts drift apart over time, which makes properties hard to compare. One shared list with a property tag gives you per-property reports and a portfolio total from the same books.
Where do mortgage payments go in a chart of accounts?
Split each payment. The interest goes to the mortgage interest expense account, and the principal reduces the mortgage payable liability. If your payment also covers property taxes and insurance through escrow, record those parts in their own expense accounts when the lender pays them.
Are security deposits income?
While you hold a deposit for a tenant, record it as a liability, since you may owe it back. If part of it is later kept for unpaid rent or damage, ask your tax professional how and when to record that amount as income.
Keep the books current
A spreadsheet chart of accounts works when every transaction gets categorized on time. KeyRing connects to your banks through Plaid, suggests where each transaction belongs for you to confirm, and shows income, expenses and profit for every property and every company as money moves. See what KeyRing does or how plans are priced, and if you are tracking rents across units, read what a rent roll is.